The Counter, Not the Vault: Sanctions Risk at Britain's Gold Buyers
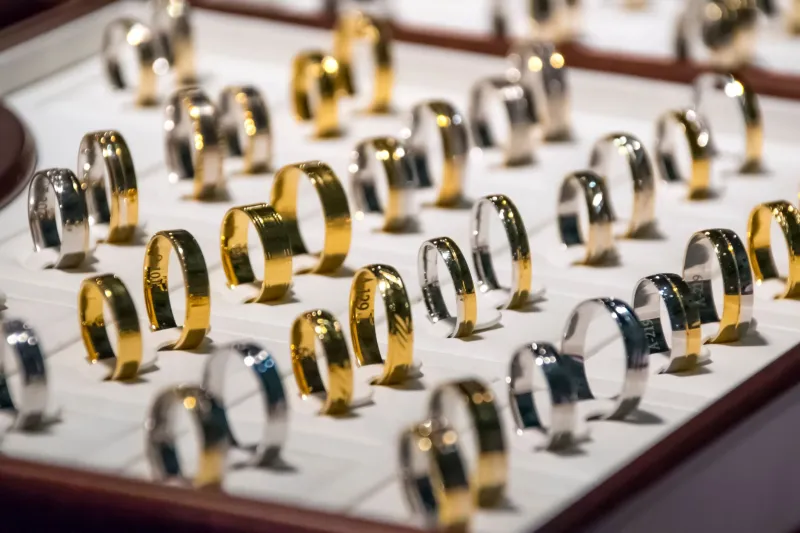
On most British high streets the sign is modest: 'we buy gold', 'cash for jewellery', 'instant valuation'. The premises are often a pawnbroker with a lending counter at the back, or a standalone dealer in a small shopping parade. The transaction is quick. A watch, a chain or a handful of rings is weighed, tested, priced and paid for. For a customer with a legitimate reason to sell, the service is useful and unremarkable. For a designated person seeking to convert an economic resource into funds, it is one of the few remaining retail routes that does not obviously pass through a bank.
The sanctions question is not whether every gold counter is a front. It is whether the supervisory architecture notices when one is used. As of November 2026, the UK's precious-metal retail sector remains a patchwork of consumer-credit authorisation, HMRC registration for high-value dealers, local trading rules and general criminal-law obligations. Those regimes overlap imperfectly. The result is a seam that runs through the ordinary shopfront rather than the imagined vault.
A portable asset with a short memory
Gold, watches and jewellery have obvious attractions for anyone trying to move value. They are portable, durable and widely understood. A high-end watch can carry a five- or six-figure value in a form that fits a pocket. Jewellery can be melted, restyled or sold on. Unlike a bank transfer, a pawn transaction does not necessarily leave a correspondent-banking trail across jurisdictions. Unlike a property sale, it does not require a solicitor, a land registry entry or a mortgage lender's source-of-funds inquiry.
Under the UK's sanctions framework, assets such as gold and jewellery can be economic resources. The prohibition is not limited to cash. Making funds or economic resources available to a designated person, or dealing with their economic resources, can amount to a breach. The €10,000 figure that dominates AML thresholds is not a sanctions threshold. A £500 chain can be an economic resource if it belongs to a designated individual. That distinction matters because the retail gold trade is built around small, quick, repeat transactions rather than single large ones.
The supervisory map has a seam
The first layer is consumer-credit regulation. A pawnbroker that lends against goods is authorised by the Financial Conduct Authority and supervised for AML as a credit firm. That does not mean every branch is inspected every year, but the firm sits inside a known supervisory relationship with reporting, training and systems obligations.
The second layer is the high-value dealer regime. HMRC supervises businesses that trade in goods and accept cash payments of €10,000 or more, including linked transactions. Registration requires an application, fitness and propriety checks and an AML programme. But the trigger is accepting cash, not paying it out. A counter whose main business is buying gold for cash is not necessarily a high-value dealer on that side of the transaction. If it also sells jewellery for large cash sums, the position may be different. The point is that the regime does not map neatly onto every 'we buy gold' shop.
The third layer is local and general. Second-hand goods dealers may face local registration requirements. Scrap-metal dealers are licensed by councils under separate legislation. Neither is an AML regime. The Proceeds of Crime Act 2002 applies across the board, and suspicious activity reports can be filed with the National Crime Agency. But a SAR is a money-laundering defence, not a substitute for sanctions screening. Sanctions breaches are reported to the Office of Financial Sanctions Implementation, and the obligations are separate.
Verification is not the same as vetted
Where customer due diligence does apply, the requirements are familiar: identify the customer, verify identity, check beneficial ownership where relevant, screen against sanctions and politically exposed person lists, and understand the source of funds and wealth. Record-keeping and ongoing monitoring follow. For a high-value dealer, CDD is required before a transaction at or above the threshold, and also where there is suspicion of money laundering or terrorist financing regardless of value.
In practice, the retail gold counter often reduces this to a photocopy of a driving licence and a recent utility bill. That establishes a name and an address. It does not establish title to the watch. It does not prove that the seller is the beneficial owner rather than a relative, an employee or a courier. It does not check whether the serial number on a watch matches a stolen-goods database. And it does not answer the sanctions question if the person in front of the counter has a clean name and a legitimate-looking story.
Sanctions screening is a name-based control. It is poor at catching asset substitution. A designated individual can ask a non-designated associate to sell the item. The associate passes ID checks, signs the declaration and takes the cash. The economic resource has left the designated person's control and become funds in someone else's hands. That is not a failure of the ID check in isolation. It is a failure of the risk assessment around the asset and the relationship.
The cash exit
Pawnbroking adds a second route. A customer can pledge an item for a loan rather than sell it outright. The item remains in the shop, but the customer receives funds. If the loan is redeemed, the item returns. If it is not, the item may be sold. Each stage has a different legal character, and each can be used to move value. The cash paid out is the point of contact with the financial system, but it is often the least documented part of the transaction.
Repeat business is the practical blind spot. A customer who brings in a bracelet one week and a ring the next may never trigger a single high-value threshold. Linked-transaction rules are meant to aggregate connected transactions, but they depend on the dealer recognising the connection and recording it. Across different branches, different towns or different company structures, that recognition is harder. There is no central register of gold purchases that a supervisor can query in the way that a bank can review account activity.
Public enforcement notices rarely feature pawnbrokers or small gold buyers. That does not prove the sector is clean. It may reflect low reporting, low inspection intensity and the difficulty of proving knowledge or suspicion in a cash-based retail environment. OFSI has shown willingness to penalise financial institutions and high-profile intermediaries. The retail precious-metal trade has not been a visible priority.
Closing the seam
The gap is structural, not scandalous. It sits between a credit regime designed for lending and an AML regime designed around cash acceptance. A risk-based response would not require every gold counter to become a mini-bank. It would require clearer sector guidance, sharper red flags and better supervisory coordination.
Three practical steps stand out. First, HMRC and the FCA should publish joint guidance on the buy-side risk in precious metals, including how linked transactions and third-party sellers should be treated. Second, dealers should be required to record asset-level information, such as serial numbers and provenance, where available, not just customer identity. Third, sanctions guidance should explicitly address the retail gold trade, including the risk of associates selling on behalf of designated persons.
None of this will eliminate the counter. Nor should it. The high street gold buyer provides a legitimate service to people who need liquidity. But a sanctions regime that depends on banks, lawyers and estate agents noticing dirty money should also look at the shop where a watch becomes cash. The counter, not the vault, is where the ordinary transaction happens. That is precisely why it deserves a closer look.